TL;DR

Get backup power and energy gear delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
Green banks are adjusting their plans amid the Trump administration’s funding freeze, concentrating on projects they can finance with private partners and existing resources. Their work continues through pooled lending, shared loan-processing systems and targeted programs, but many operate on annual budgets below $2 million. The source report does not specify the freeze’s full scope or when affected funding might resume.
Green banks are scaling back or narrowing the projects they pursue as they navigate the Trump administration’s funding freeze, turning toward private lenders and deals they can still support. The shift is shaping financing for energy-efficiency upgrades, solar and electrification projects, particularly for customers who have difficulty obtaining conventional loans.
Rather than take on the higher-risk projects they might otherwise pursue, green banks are concentrating on financing that can attract private capital. In the Canary Media report, an unidentified speaker named Adler said the immediate focus is “tight discipline with private capital as our key partner.” The strategy, he said, is to finance projects that remain difficult for commercial lenders, then demonstrate that they can work so private lenders may take over.
Green banks often address risks tied less to the technology than to the borrower or size of a deal. Adler said customers such as affordable-housing providers and solar developers serving low-income communities can face barriers in traditional credit markets. Green banks take on credit, deal-structure and scale risks, he said. One approach is to combine money from multiple lenders, spreading exposure across partners.
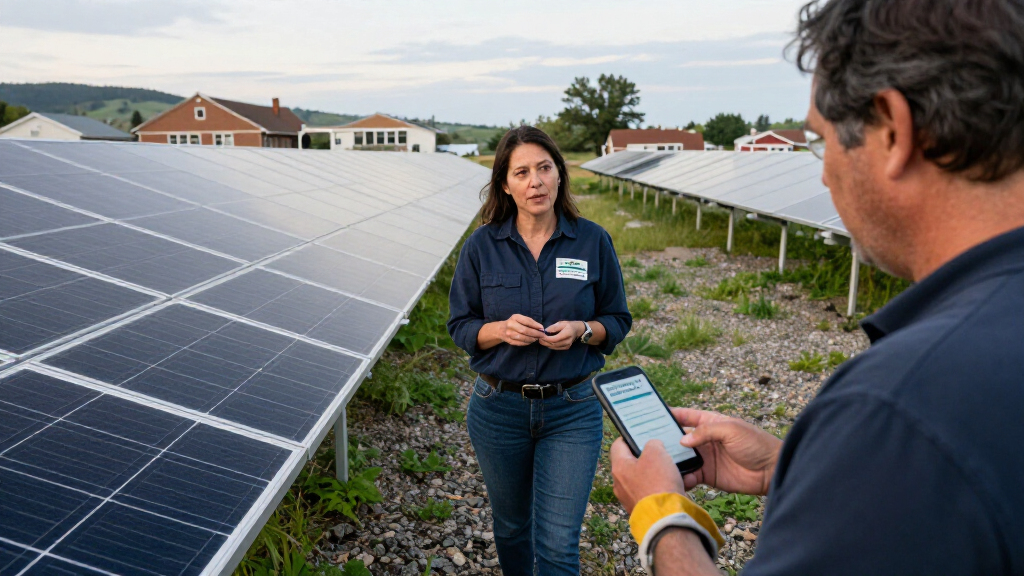
The report describes other ways organizations are keeping lending activity moving. The Florida-based Solar and Energy Loan Fund has developed a standardized lending platform used by 13 other green banks and similar lenders, according to its chief of staff, David Graber. Montgomery County Green Bank in Maryland launched a $4 million initiative in March 2026 offering low-interest financing for household solar, heat pumps and other improvements. Its qualifying homeowners can access solar loans at a subsidized 2.99% interest rate for the first 15 years, with a higher rate afterward, said Rokas Beresniovas, the bank’s head of partnerships and business development.
How the Freeze Reshapes Lending
The shift matters because green banks are designed to finance projects and borrowers that private lenders may judge too small or risky. If public or federal funding is unavailable, organizations may have less capacity to take on that early risk, even when projects could later attract commercial financing. The report describes a narrower approach: prioritize deals with a clear path to private participation, rather than pursue the full range of projects a green bank might otherwise support.
The stakes extend to households and community organizations seeking lower energy costs or access to clean-energy improvements. Green bank loans can help pay for measures such as solar panels and heat pumps, while financing for affordable housing can support all-electric buildings. The report does not quantify how many projects have been delayed or canceled, but it shows how the funding environment is affecting the kinds of deals institutions say they can pursue.
Green banks are public, nonprofit or quasi-public finance organizations that use lending and other financial tools to support clean-energy projects. The report says the first green banks in Connecticut and New York, formed in the 2010s, helped drive private-sector lending for building efficiency, electrification and solar projects for schools and municipalities. Their role includes financing projects that conventional lenders may not readily serve, then helping establish a record that can make later lending more attractive to private capital.
The report gives examples of risk-sharing and support. Inclusive Prosperity Capital and partners bundled funding for a community solar project serving the Sisters of the Holy Family. New York City Energy Efficiency Corp. worked with Utah nonprofit SustainEnergyFinance on a $4.5 million predevelopment loan for a 396-unit all-electric affordable-housing project in Salt Lake City. The loan supported the developer’s move into later construction stages. These examples illustrate existing financing methods; the report does not say they were directly caused by the current freeze.
Shared systems are another way to stretch limited capacity. Graber said the Solar and Energy Loan Fund platform lets partner lenders use back-office expertise without each building a full lending operation. The organization estimates that each partner avoids hundreds of thousands of dollars annually in operating costs. The Green Bank 50 report, cited by Canary Media, says many green banks have annual budgets below $2 million.
““We provide the back office and the capital. Partners bring the local trust and the projects.””
— David Graber, chief of staff at the Solar and Energy Loan Fund
What the Freeze Leaves Unclear
The source report does not detail which specific federal programs or sums are covered by the funding freeze, how long it is expected to last, or whether funding has been formally canceled rather than paused. It also does not provide a count of green banks that have reduced lending, the value of affected projects, or a comparison with lending before the freeze.
It is unclear how many projects can proceed using private capital, local funds or existing loan programs, and how many will be delayed or abandoned. The examples in the report show financing activity continuing, but they do not establish that every institution has the same access to replacement funding or that the programs described can make up for any lost federal support.
Whether Private Capital Fills Gaps
The next test for green banks is whether private lenders will participate in the projects they continue to pursue and whether shared platforms and local financing initiatives can sustain lending while federal funding remains uncertain. The reported Maryland initiative and partner-lending platform offer examples of current activity, but the source does not give timelines for future federal funding decisions.
Further developments to watch include any clarification from the administration or funding agencies about the freeze, and whether green banks report changes in loan volume, project pipelines or available capital. Until those details emerge, the extent of the freeze’s practical effects on specific communities and projects remains unsettled.
Key Questions
What are green banks doing in response to the funding freeze?
According to the report, they are focusing on deals they can support with private lenders, sharing lending services and using targeted programs to keep some financing available.
What kinds of projects do green banks finance?
The examples include energy-efficiency improvements, rooftop solar, heat pumps, community solar and all-electric affordable housing. Green banks also work with borrowers and projects that may have trouble securing conventional loans.
Has the report quantified how many projects are affected?
No. It describes organizations’ financing strategies and selected programs but does not give a total number or value of projects delayed, canceled or otherwise affected by the freeze.
What is the Maryland loan program described in the report?
Montgomery County Green Bank launched a $4 million initiative in March 2026 for household solar, heat pumps and other improvements. Qualifying homeowners can access solar loans at a subsidized 2.99% rate for 15 years, followed by a higher rate, according to the bank’s head of partnerships and business development.
When will federal funding resume?
The source does not state whether or when the funding freeze will end or whether the affected funding will be restored.
Source: rss
Columbus Day / Indigenous Peoples' Day Picks
long weekend sales
As an affiliate, we earn on qualifying purchases.